
 0
 0
Yes, you can start a real estate business in Canada with little or no money, and you don’t need a stack of savings or a rich investor to do it. The most realistic path is to begin with models that sell your time, skills, and hustle instead of your cash: working under a licensed brokerage, wholesaling, property management, or partnering with someone who has the capital while you bring the legwork. Expect to spend a few weeks on preparation and a few months building your first deal, and know that the main prerequisite is a willingness to learn the rules in your province.
Those rules matter. In Canada, real estate is regulated provincially, so what you can legally do without a licence depends on where you live. Some activities require registration. Others don’t. Knowing the difference early keeps you safe and keeps your reputation clean.
The good news is that plenty of Canadians have built real businesses from a laptop, a phone, and a solid plan. This guide walks you through the low-cost models that actually work, the free tools and funding resources worth using, the licensing and safety flags to watch, and a clear 7-step process you can start today. Let’s get you from “I have no money” to “I have my first move.”
What ‘No Money’ Really Means in Real Estate (and Which Paths Fit)
Start With Services, Not Properties
Buying property takes a down payment, a mortgage approval, and a lot of risk. Selling your time, skills, and local knowledge takes none of that, which is why services are the easiest door into real estate when you’re starting with little cash.
Think about what people in your community already pay for. Someone needs a tenant screened, a unit cleaned between renters, a listing photographed, a vacant home checked on, or a buyer introduced to the right agent. These are real jobs with real fees, and you can start doing them with a phone, a laptop, and a bit of hustle.
Services also pay you sooner. A referral fee, a property management contract, or a small coordination job can put money in your account within weeks, not years. That cash covers your licensing course, business registration, and marketing without touching your savings.
There’s a quieter benefit too. Every job you finish builds your reputation and your list of contacts: landlords, investors, contractors, and agents who now know you deliver. Those relationships are what open the door to bigger deals later, including partnering on a first property.
Start by listing the skills you already have, then match them to a local need. Small, steady wins add up faster than most beginners expect.
Choosing the Model That Matches Your Skills and Province
Your best model is the one that fits what you already do well, so start there instead of copying someone else’s path.
If you’re a natural talker and enjoy meeting people, sales-driven roles like referrals, lead generation, or working under a brokerage can suit you. If you’re organized and detail-minded, property management or coordinating showings and paperwork may be a better fit. Strong networkers often do well in wholesaling, since the job is connecting motivated sellers with the right buyers. And if you’re handy with tools or good at spotting repair costs, you could build a small business around light renovations, staging, or preparing properties for sale.
Try a quick exercise. Write down your top three strengths, then list the real estate tasks where each one would matter most. Patterns show up fast, and that gives you a confident place to begin.
Next, check the rules where you live. Real estate is regulated differently across Canada, and what’s allowed in Ontario may not match what’s allowed in British Columbia or Alberta. Activities like trading in real estate for others, earning commissions, or even marketing certain deals can require provincial or territorial licensure. Your provincial real estate regulator’s website is the best first stop for what’s permitted and what isn’t.
Pick one model that matches both your skills and your local rules, and give it a fair try. You can always add a second service later once you’ve built some momentum.
What You Need Before You Begin: Free and Low-Cost Tools and Resources
Free Learning and Market Research Sources
You don’t need an expensive course to learn how local real estate works. Start with your public library. Many Canadian branches offer free access to market reports, business databases, and books on real estate fundamentals, plus quiet space to study.
Next, visit your provincial real estate regulator’s website. These sites explain licensing requirements, the rules agents must follow, and how consumer protection works in your area. Reading them early shows you what’s allowed before you take any step.
For market research, look at municipal websites. Many cities publish zoning maps, development applications, and building permit data for free. Reading these will show you which neighbourhoods are growing, where new projects are planned, and where demand might be heating up.
You can also browse public listings on major Canadian real estate sites to track asking prices and how fast homes sell in your target area. Finally, look for free online courses from colleges, universities, and open learning platforms. Even a few hours each week adds up, and the knowledge you build now will help you speak confidently with future clients and partners.
Funding Support to Explore Along the Way
Starting small doesn’t mean you have to go it alone. Several kinds of funding can help with the modest costs of getting licensed or getting your name out there, and it’s worth knowing what’s on the table before you spend a dime of your own savings.
Start with small business grants. Federal, provincial, and municipal programs sometimes offer funding for new entrepreneurs, and some target specific groups such as youth, women, Indigenous founders, or newcomers to Canada. Grants don’t need to be repaid, but they’re competitive and the rules vary a lot by region, so read the eligibility details closely.
Microloans are another option. These are small loans, often a few thousand dollars, designed for startups that don’t have a long financial history. They can cover things like exam fees, a basic website, or business cards while you land your first deal.
Startup credit options, such as a business credit card or a small line of credit, can smooth out cash flow. Use them carefully and only for costs you can realistically repay from early commissions or fees.
None of these come with a guarantee. Approval depends on your plan, your province, and the program’s criteria, so treat funding as a bonus rather than a requirement. A clear, well-organized plan will help you put your best foot forward whenever you decide to apply.
Protect Yourself First: Licensing, Legal, and Money Safety Checks
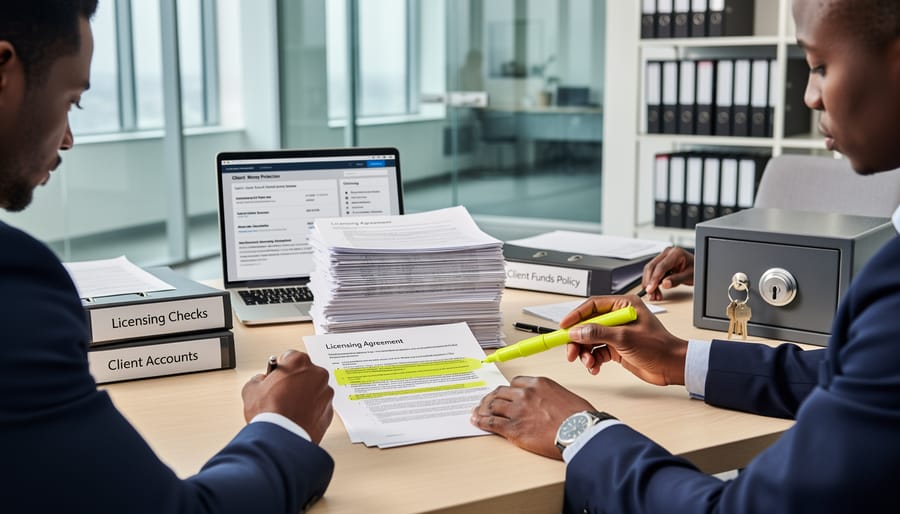
Starting with little money doesn’t mean cutting corners on safety. The habits below protect you and your clients, and they quickly earn you a reputation as someone people can trust.
Begin by confirming your province’s licensing rules before you earn a single dollar. Some activities need a licence, while others, like certain property management or administrative support roles, may not. Your regulator’s website is free to read, and a quick phone call can save you from fines or a damaged reputation. If you’re still deciding how to build your first income stream, you can also explore low-cost ways to start from home while you sort out the licensing requirements.
Next, build a few simple habits into everything you do:
– Stay inside the rules. Avoid unregulated deals and side arrangements, even when someone offers to “keep it quiet.” If a deal can’t be done openly, it isn’t worth doing.
– Never guarantee returns. Real estate values and rents move, so promise your effort and honesty, not profits. Overpromising is one of the fastest ways to lose a client’s trust.
– Read every contract carefully. Take your time with each clause, ask questions, and get a lawyer’s opinion on anything you don’t fully understand.
– Keep client funds separate. Never mix a client’s money with your own, and use proper channels for deposits and payments.
Finally, know when to walk away. Be wary of any deal that asks for large upfront fees, pushes you to decide immediately, or leaves you with more questions than answers. Pressure is a warning sign, and good opportunities will still be there after you’ve had time to think and check the details.
These checks may feel like extra work at first, but they become second nature quickly. Handled well, they set you up for steady referrals and a business you can grow with confidence.
How to Start a Real Estate Business With No Money: 7 Steps
Steps 1 to 3: Choose, Learn, and Get Compliant
Step 1: Choose your model and niche. Pick one low-cost model, such as wholesaling, referrals, or property management, and one focus, like rentals in your city or first-time buyers in your neighbourhood. Narrow beats broad when you have no budget. A clear niche makes you easier to remember and recommend.
Step 2: Learn your local market for free. Spend a few weeks reading public listings, municipal permit and zoning pages, and local news about development. Note typical rents, how long homes take to sell, and which areas are heating up. Your public library often offers free business databases and market reports, and many of them are worth a visit.
Step 3: Get compliant before you earn. Rules vary across provinces and territories, so check your provincial real estate regulator’s website first. Find out whether the activity you chose needs a licence, and what happens if you act without one. Never collect a fee or commission until you know where you stand.
As you go, write everything down in the Business Plan Builder. Capture your model, niche, target area, and licensing notes in one place. By the end of step 3, you’ll have a simple plan to follow, and that’s a real head start.
Steps 4 to 5: Set Up and Build Your Network
Once you’ve chosen your model, it’s time to make it official without spending much. Register a sole proprietorship or a simple business name through your province’s online registry. Fees vary, but they’re often modest, and you can upgrade to a corporation later when income justifies it. Check your provincial rules first, since real estate activity may carry extra requirements.
Next, build a free online presence. Set up a professional LinkedIn profile, a Google Business Profile, and a simple social page showing your area expertise. This is low-cost marketing that works because local trust matters more than a flashy budget.
Then comes the real engine: people. Attend local real estate investor meetups, chamber of commerce events, and community association meetings. Introduce yourself to agents, mortgage brokers, contractors, and property managers. Ask questions, offer to help, and follow up. If you’re unsure where to begin, startup mentorship programs can connect you with experienced guides who open doors.
Plenty of Canadian newcomers to the industry have started by working under an established brokerage or teaming up with an experienced investor, learning the ropes while earning income and building a client base. They brought hustle and local knowledge. Their partners brought credibility and capital.
Keep every conversation friendly and genuine. Today’s coffee chat could become next year’s first referral.
Steps 6 to 7: Win Your First Deal and Grow From There
Once your network is in place, the goal is simple: close one real deal. Start by bringing value to someone who already has capital. Many investors have money but lack time to find, screen, or manage opportunities. If you can source a property, organize the paperwork, or handle tenants, you become a useful partner. Be upfront about what you offer and what you expect in return, and get every arrangement in writing. Check your province’s rules before taking any fee, since some activities require a licence.
To attract funding partners, put your idea on paper. A short pitch deck works well: describe the opportunity, the numbers, the risks, your role, and how the investor gets paid. Canadian StartUp’s Investor PitchDeck tool can help you lay this out clearly, even if you’ve never pitched before. Keep it honest and realistic. Investors trust beginners who show their homework and don’t promise guaranteed returns.
When your first deal pays out, resist the urge to spend it all. Reinvest in steps that build lasting value:
1. Licensing or training that opens up more types of deals
2. Simple marketing, like a basic website or business cards
3. A down payment fund toward your first property
Small, steady wins add up quickly. Each deal builds your reputation, and a good reputation brings the next opportunity to you.
How to Check You’re on Track and What to Do Next
You’ll know your real estate business is taking shape when small, concrete things start happening. A stranger asks about your service. A client signs your first agreement. Leads trickle in each week without you chasing them. Someone says they’d recommend you. None of these needs to be big. Each one tells you the model is working.
Keep your tracking simple. Open a basic spreadsheet with a few columns: date, lead source, inquiry, outcome, and money earned or spent. Add a monthly tally of new leads, signed agreements, and total costs. After a few weeks, patterns show up. You’ll see which source brings the best leads, which service pays fastest, and where your time is leaking away.
Once you have steady activity, decide what comes next. If a licence, marketing, or a first property purchase is the hurdle, look into small business grants and microloans. Many Canadians also find that credit union loans offer friendlier terms for new owners than the big banks, so they’re worth a conversation. Bring your spreadsheet with you. Real numbers, even small ones, show a lender you’re serious.
You can also strengthen your pitch. Use what you’ve learned to refine your story for investors or partners, then think about adding a second service line, such as property management alongside referrals. Growing one step at a time keeps risk low.
To stay on course, return to Canadian StartUp’s Business Plan Builder, Small Business Startup Database, and Investor PitchDeck. Updating your plan as you learn keeps your momentum going.
Common Questions About Starting a Real Estate Business Without Money
Most people have the same handful of worries before they begin, so let’s tackle them head on. The answers below are general guidance for Canada, and the details can differ by province, so always confirm with your local regulator.
Do I need a licence to start?
It depends on what you do. Earning commission from buying or selling property for others generally requires a licence from your provincial regulator, while some services, like helping with property tours or doing referral-style networking, work differently. Check your province’s rules before you earn a dollar.
Can I buy investment property with no money down in Canada?
It is very hard. Lenders usually want a down payment, so most beginners start with service-based models and partner with investors who bring the capital while they bring time, effort, and local knowledge.
How long until I earn my first income?
There is no fixed timeline. It depends on your model, your market, and how quickly you build relationships, so focus on steady weekly actions rather than a deadline.
Can I do this part-time while keeping my job?
Yes, many people begin in evenings and weekends. Starting part-time lets you learn the market and build a small network while your paycheque covers the basics.
A few other questions come up often. Are there grants for real estate startups? Funding options exist for small businesses in general, but they rarely target real estate directly, so explore microloans and startup programs for help with licensing or marketing costs, and don’t expect approval to be guaranteed.
What are the biggest beginner mistakes to avoid? Rushing into deals before confirming licensing rules, signing contracts you haven’t read carefully, and promising returns to anyone are the big ones. Taking a little extra time to learn locally protects both you and the people who trust you.
You don’t need to have every answer before you start. Pick one question that’s holding you back, find the answer for your province, and take the next small step.
You don’t need a big bank balance to get into real estate. You need a plan, a willingness to learn, and a few good people in your corner. Start small with a service-based model, check your provincial licensing rules, and build your reputation one honest conversation at a time. Every referral, every signed agreement, and every lesson learned locally moves you closer to bigger deals, and it all starts with the first step.
That’s the heart of any smart approach to starting a business without money. You lean on what you already have: your time, your skills, your community, and a bit of curiosity. The capital tends to follow once people see you deliver.
So don’t wait for the “perfect” moment or a bigger savings account. Open the Business Plan Builder at Canadian StartUp today and map out your first real estate idea. Then browse the Small Business Startup Database to find the resources, programs, and funding options that fit your province. You’ve got this, and your first move can happen today.



Average Rating